Dwelling & other structures
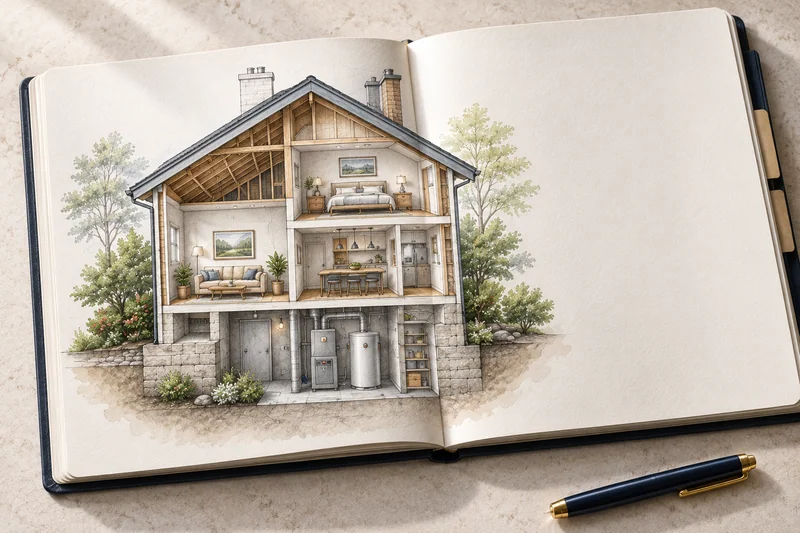
Protection for the house and certain separate structures after a covered loss, subject to the policy’s limits and terms.
Homeowners insurance · Serving Indiana statewide
Your home changes over time. Your coverage deserves a closer look, too. Let’s review what protects the house, what protects your belongings, and what may need a separate conversation.
Built around your real life
The price you paid for a home and the cost to rebuild it are different questions. Renovations, materials, labor, and the features of your home all belong in the conversation. John can help you review your policy against the home you have today.
Quotes from multiple insurance companies. Guidance for clients across Indiana. Available options depend on your needs and the insurer’s requirements.
Understand the building blocks
Use these topics to guide a review. Available products, limits, endorsements, and eligibility depend on the insurer and your situation.
Protection for the house and certain separate structures after a covered loss, subject to the policy’s limits and terms.
Coverage for eligible belongings. Compare actual cash value and replacement-cost terms, item limits, and any scheduling needs.
Eligible extra costs if a covered loss makes the home unlivable. Time limits and dollar limits matter.
Protection for certain claims alleging injury or property damage for which you are legally responsible.
Certain eligible guest medical expenses, subject to policy terms. This differs from your household’s health coverage.
Review applicable deductibles and how depreciation, repair requirements, and special provisions affect a claim.
Look at the details
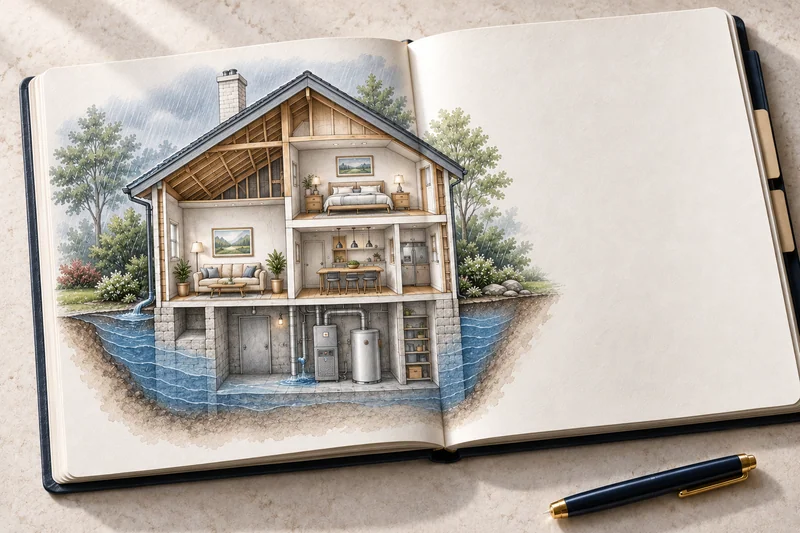
Flooding, a backed-up drain, and a burst pipe can raise different policy questions. Standard homeowners insurance typically excludes flood damage. Ask separately about flood insurance and any water-backup endorsement that may apply to your property.
Talk it through with the agencyFloodingRising surface water, such as runoff.
Water backupA drain, sewer, or sump-system backup.
A burst pipeWater escaping from damaged plumbing.
Different water sources raise different policy questions. Ask which terms, exclusions, endorsements, or separate coverage apply.
Put the policy in context
These hypothetical examples show what to ask. They do not determine whether a claim would be covered.
A covered fire may raise separate questions about the dwelling, damaged belongings, and extra living costs while repairs take place. Review the limit and settlement terms for each part instead of assuming one total answers everything.
If we need to live elsewhere during covered repairs, what dollar and time limits apply?
New flooring, furniture, and equipment can change your rebuilding and belongings needs. A backed-up drain and rising floodwater may fall under different coverage terms; the same damaged room does not mean the same protection.
Which water losses are covered, excluded, or available through an endorsement or separate policy?
For a hypothetical $12,000 covered repair, a $1,000 deductible leaves a different starting responsibility than a $2,500 deductible. That simple subtraction is not a claim estimate: depreciation, exclusions, special deductibles, and policy limits can change the result.
Which deductible applies to this cause of loss, and how would settlement work?
Make the conversation count
You don’t need to arrive with every answer. These details can help the agency understand where you are starting.
Current declarations pages and renewal date
Recent improvements, roof updates, and high-value belongings
Questions about deductibles, water damage, and rebuilding
Use the agency’s requested secure process for sensitive application information. Please do not email Social Security numbers or medical records.
A little clarity before we talk
Understand the details before you decide.
Start with an estimate of the cost to rebuild, then review belongings, liability, and additional living expenses. A mortgage balance or market price alone does not answer each of those questions.
No. The cause of the water and the policy’s wording matter. Flood and water backup can require separate coverage discussions. Ask which exclusions, endorsements, and deductibles apply to your home.
Yes. An addition, finished basement, updated kitchen, or other improvement can change the home and its rebuilding needs. Tell your agent about changes and confirm whether your coverage should be updated.
Yes. Reviewing them together can help you understand how liability limits, deductibles, and available bundling options fit. Eligibility and any discounts depend on your circumstances and policies.
See the bigger picture
Your next question may connect to another part of your coverage.
Think about how your policies work together.
Start before water is at the door.
Based in Carmel. Serving all of Indiana.
Bring your current policies and your questions. We’ll help compare available quotes from multiple insurance companies and put the details in context.
